Applied Mathematics
Pricing European Options under Logistic Stock-Price Dynamics with a Continuous Dividend Yield
Department of Mathematics, Kibabii University, Bungoma, Kenya
Published October 2026
Abstract
Logistic stock-price dynamics have been proposed as a way of representing assets whose growth is bounded by competition, saturation or finite market capacity, but the derivations available in the literature retain a logistic drift while invoking a delta-hedging argument that removes it. This paper resolves that inconsistency and extends the framework to dividend-paying assets. It is first shown that, for a traded asset, no-arbitrage forces the logistic term out of the pricing equation; the logistic model is therefore developed as an incomplete-market model in which a state-dependent market price of risk fixes the pricing measure, and the pricing partial differential equation is obtained from the Feynman–Kac representation rather than from hedging. The resulting equation carries a continuous dividend yield and reduces to the Black–Scholes–Merton equation as the carrying capacity grows without bound. A closed-form solution of the price process is derived through the reciprocal transformation, which linearises the stochastic logistic equation and expresses the price as a geometric Brownian motion divided by an exponential functional. Prices are computed by a Crank–Nicolson scheme with Rannacher start-up; second-order convergence is demonstrated and the scheme is cross-validated against Monte Carlo simulation of the closed-form representation. Sensitivity analyses quantify the effect of carrying capacity, dividend yield and volatility, and a forward-price diagnostic measures the departure from put–call parity, for which a first-order analytic expression is derived and verified numerically.
Keywords: carrying capacity; Crank–Nicolson scheme; dividend yield; European options; Feynman–Kac representation; incomplete markets; logistic diffusion
1Introduction
The Black–Scholes–Merton framework [1, 2] remains the reference model for the valuation of European options. Its tractability rests on the assumption that the underlying asset follows a geometric Brownian motion, so that the asset grows exponentially in expectation and is unbounded above. For many assets this is an adequate idealisation. For others it is not: firms operating in saturated product markets, regulated utilities, licensed operators facing a fixed subscriber base, and frontier-market counters with limited free float all display growth that slows as the asset approaches a ceiling imposed by the size of the market rather than by the behaviour of investors.
The logistic law of Verhulst [13] is the canonical description of such bounded growth, and its stochastic version has been used in mathematical finance by Onyango [11], Oduor, Omolo, Okelo and Onyango [10], Nyakinda [9] and Mulambula, Oduor and Kwach [8]. The attraction is clear: the logistic drift introduces a carrying capacity at which expected growth vanishes, and it recovers the exponential case in the limit of infinite capacity.
Two problems recur in that literature, and both are addressed here. The first is a derivation problem. The standard route to a pricing equation is the delta-hedged portfolio of Black and Scholes. When that argument is applied to a traded asset it eliminates the drift of the asset entirely, so the logistic factor cannot survive into the pricing equation; papers that display a logistic pricing equation obtained by hedging are internally inconsistent. The second is an evidential problem: numerical schemes are named rather than specified, and sensitivities are asserted rather than computed.
This paper makes four contributions. First, it states precisely why the hedging argument is unavailable for this model and constructs the pricing measure explicitly through a state-dependent market price of risk, so that the pricing equation follows from the Feynman–Kac representation. Second, it incorporates a continuous dividend yield into that construction. Third, it derives a closed-form representation of the price process by way of a reciprocal transformation that linearises the stochastic logistic equation, and identifies the exponential functional of Brownian motion that obstructs a simple closed-form option price. Fourth, it provides a fully specified and validated numerical treatment, together with a quantitative diagnostic of the model’s departure from put–call parity and a first-order analytic expression for that departure.
The remainder of the paper is organised as follows. Section 2 reviews the relevant literature. Section 3 sets out the market, the assumptions and the choice of pricing measure. Section 4 derives the pricing equation and its auxiliary conditions. Section 5 gives the closed-form solution of the price process. Section 6 specifies the numerical method and validates it. Section 7 reports the numerical results and the sensitivity analysis. Section 8 presents the forward-price diagnostic. Section 9 treats calibration, Section 10 discusses the findings and their limitations, and Section 11 concludes.
2Related literature
Departures from geometric Brownian motion fall into three broad families. The first modifies the diffusion coefficient: the constant elasticity of variance model of Cox and Ross [3] and the local volatility surfaces of Dupire [5] and Derman and Kani [4] reproduce the observed smile while preserving the martingale property of the discounted asset. The second adds jumps, as in Merton [7] and Kou [6]. The third makes volatility itself stochastic, as in Heston [12]. In all three families the risk-neutral drift of a traded asset remains the risk-free rate net of dividends, because no-arbitrage requires it.
Logistic models sit outside these families precisely because they modify the drift. Onyango [11] extracted logistic dynamics from market price data by pattern recognition; Oduor et al. [10] estimated volatility under logistic Brownian motion; Nyakinda [9] derived a non-linear logistic Black–Scholes–Merton equation; and Mulambula et al. [8] combined logistic dynamics with a jump-diffusion component. These studies establish the empirical motivation for bounded growth. What they do not do is reconcile a non-martingale risk-neutral drift with the absence of arbitrage, or price dividend-paying assets within the logistic framework.
The theory needed for that reconciliation is standard but has not been applied here. In an incomplete market a contingent claim is priced under an equivalent martingale measure that is not unique; the selection of a measure is a modelling decision, and Karatzas and Shreve [14], Duffie [15] and Björk [16] give the conditions under which the Feynman–Kac representation then yields a linear parabolic pricing equation. Dividend-paying underlyings are treated by Merton [2]. On the analytical side, the reciprocal transformation of the stochastic logistic equation is classical, and the law of the resulting exponential functional of Brownian motion has been studied by Dufresne [17] and Yor [18]. On the numerical side, the Crank–Nicolson scheme [19] requires the start-up damping of Rannacher [20] when the terminal condition is only piecewise smooth, as it is for a vanilla payoff; Giles and Carter [21] analyse the resulting convergence.
The gap addressed by this paper is therefore specific: a logistic option pricing model for dividend-paying assets, derived consistently, solved to a stated accuracy, and diagnosed for the arbitrage implications that the drift modification necessarily carries.
3Model formulation
3.1Market and assumptions
Fix a finite horizon T > 0 and a filtered probability space carrying a standard Brownian motion. The following assumptions are maintained throughout.
- A1. The risk-free rate r, the dividend yield q, the volatility σ and the carrying capacity N are positive constants.
- A2. Trading is continuous and frictionless; there are no transaction costs, taxes or short-sale restrictions.
- A3. The underlying pays dividends continuously at the proportional rate q.
- A4. The underlying is not perfectly replicable by a self-financing portfolio of the bond and a liquid traded proxy; the market is therefore incomplete.
- A5. Option payoffs are European and depend on the terminal value of the underlying alone.
Assumption A4 is the substantive one and is discussed in Section 3.3.
3.2Stock-price dynamics under logistic growth
Under the physical measure the price St is assumed to satisfy the stochastic logistic (Verhulst) equation
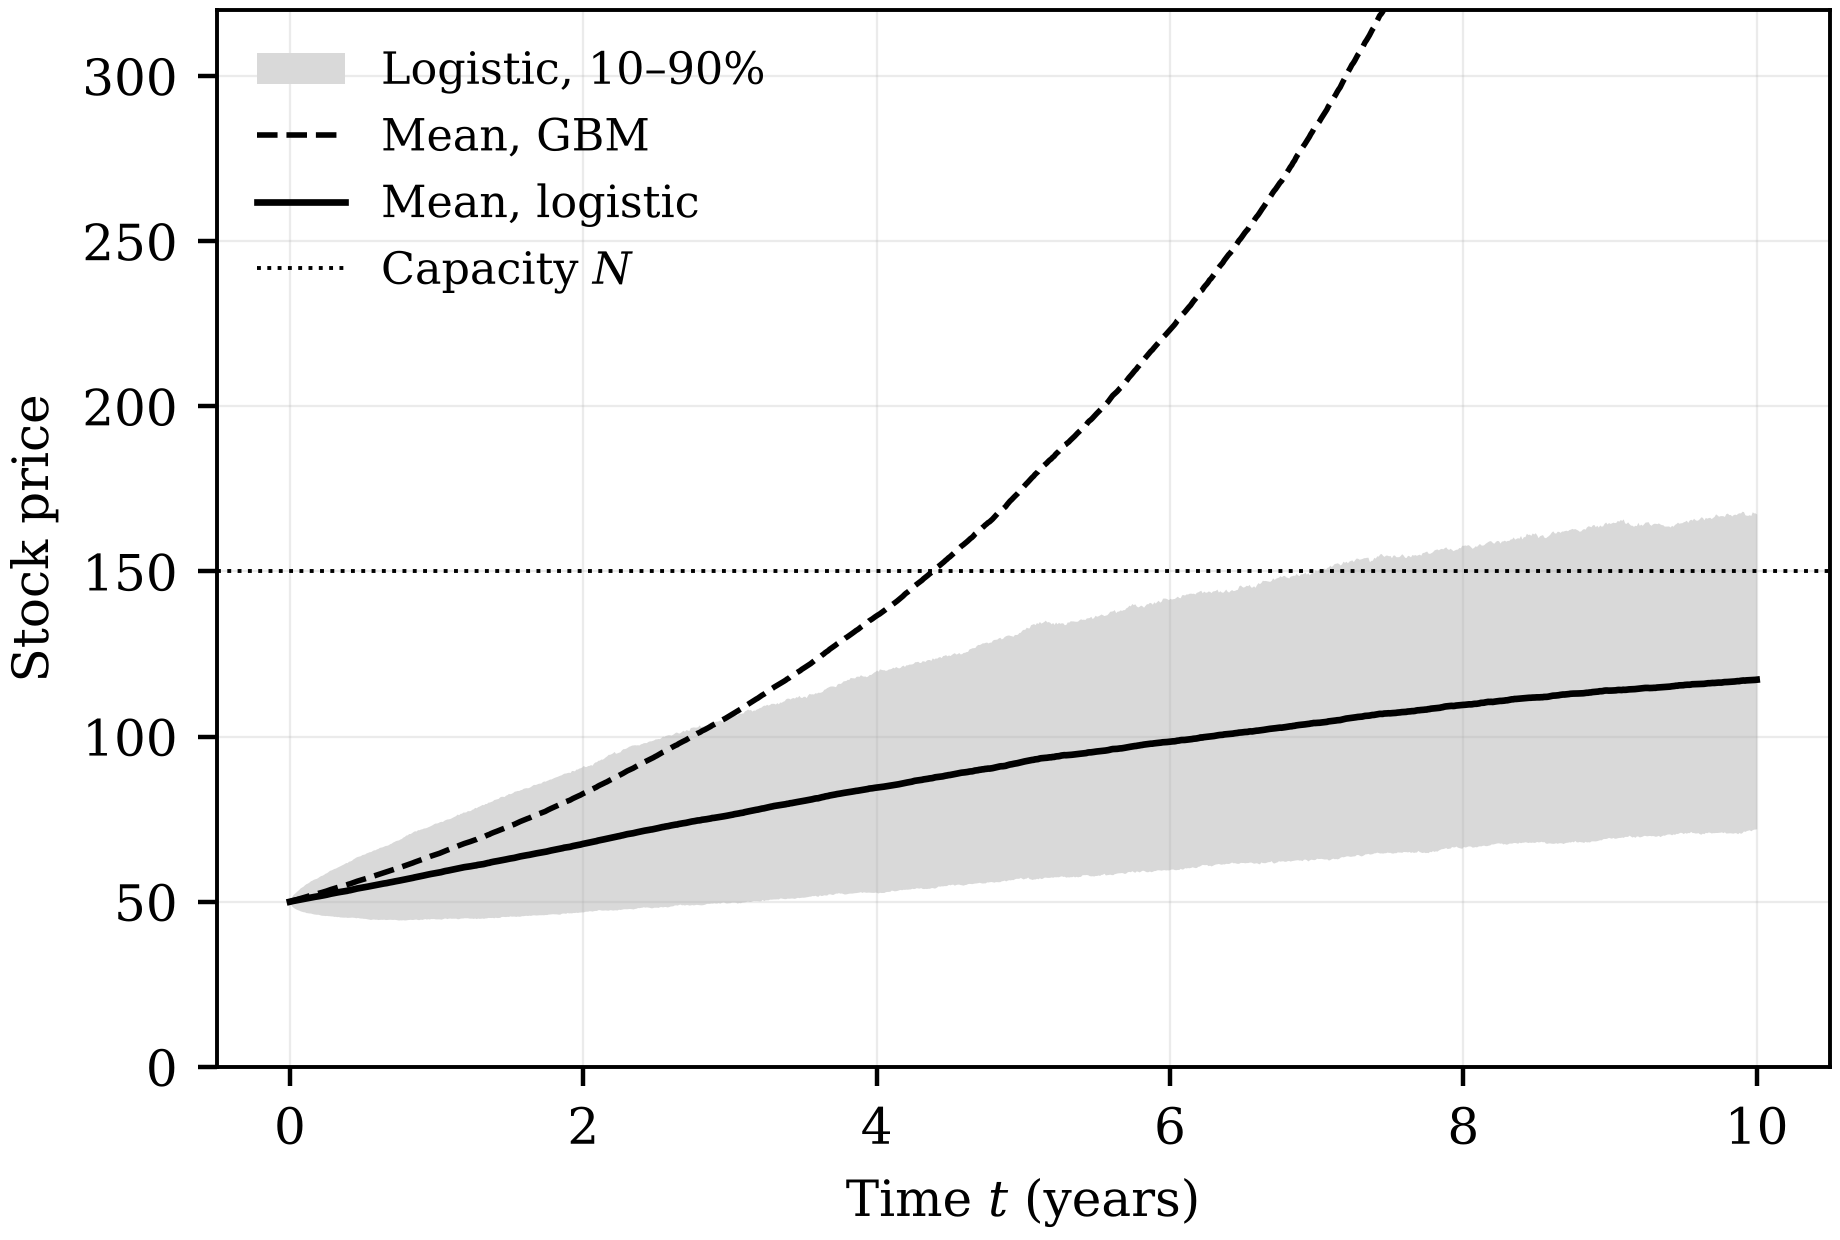
where μ is the intrinsic growth rate and N is the carrying capacity. When St is small relative to N the drift is approximately μSt and the process behaves like a geometric Brownian motion; as St approaches N the drift vanishes and growth stalls. Because the noise is multiplicative, N is a level of vanishing drift rather than an absorbing barrier: excursions above N are possible, and there the drift is negative, pulling the process back. Figure 3 illustrates the mechanism.
3.3Dividends and the choice of pricing measure
Two readings of (1) must be separated.
Reading 1 (traded, replicable asset). Suppose the underlying is traded and a self-financing portfolio Π = V − (∂V/∂S)S is formed. Applying Itô’s lemma and the dividend adjustment, the terms in dS cancel identically, and the drift of the underlying disappears from the resulting equation whatever its functional form. The pricing equation obtained is
which is the Black–Scholes–Merton equation with a dividend yield: the logistic factor is annihilated by the hedge. Any derivation that hedges and then retains the logistic drift contradicts itself. This point is stated here because it is the error most frequently encountered in the logistic option pricing literature.
Reading 2 (incomplete market). Suppose instead that the underlying cannot be perfectly hedged, as in Assumption A4. Then the equivalent martingale measure is not unique, and a measure is selected by specifying a market price of risk. Choosing the state-dependent form
and applying Girsanov’s theorem gives the dynamics under the selected pricing measure Q,
The logistic structure is preserved under Q, and the intrinsic growth rate μ has been replaced by the cost-of-carry a = r − q. Equation (3) is a modelling choice, not a consequence of no-arbitrage; its economic content is that the risk premium demanded by investors scales with the remaining growth headroom of the asset. Section 8 quantifies the price of this choice. All subsequent results are stated under Reading 2.
4The pricing equation
Let Ψ denote the terminal payoff and define the value function by risk-neutral valuation,
Since the coefficients of (4) are locally Lipschitz on (0, ∞) and of linear growth, and the payoff is of polynomial growth, the Feynman–Kac representation applies and V solves the backward parabolic equation
on (0, ∞) × [0, T). Equation (6) is the pricing equation of the model. Three properties are worth recording.
- 1. It is linear, despite the non-linearity of the drift in S; the non-linearity enters as a variable coefficient, not as a non-linear term in V. Standard linear parabolic theory therefore applies.
- 2. As N → ∞ the coefficient of the first derivative tends to (r − q)S and (6) reduces to (2), the Black–Scholes–Merton equation with a continuous dividend yield. The model is thus nested.
- 3. The dividend yield enters only through the combination a = r − q in the drift, while the discount rate remains r; this asymmetry is what generates the dividend sensitivities reported in Section 7.
4.1Auxiliary conditions
For a European call with strike K the terminal condition is
with boundary conditions
For a European put the terminal condition is
with
The far-field condition is imposed as vanishing gamma rather than as the Black–Scholes asymptotic value. This is deliberate: under logistic dynamics the large-S asymptotics differ from the exponential case, and a linearity condition is both correct in the limit and robust to the choice of truncation point.
5Closed-form solution of the price process
Although (6) admits no simple closed-form solution, the price process itself does. This is the content of the following result, which also explains where the analytical difficulty actually lies.
Proposition 1. Let S satisfy (4) and set X = 1/S. Then X satisfies the linear stochastic differential equation
Setting
the explicit solution is
Proof. Apply Itô’s lemma to X = 1/S, using dX = −S−2dS + S−3(dS)². The quadratic variation term contributes σ²X dt, and the logistic term a S(1 − S/N)S−2 collapses to −aX + a/N, which is affine in X. The equation is linear with multiplicative noise, and the integrating factor Φ given in (12) yields (13) by the variation-of-constants formula.
Corollary 1. Inverting the transformation and writing
the solution of (4) is
so that St is a geometric Brownian motion with drift a, deflated by an exponential functional of Brownian motion. The option price is therefore
Corollary 1 has three consequences. It shows that the model is exactly simulable up to the discretisation of the integral, which is what makes the Monte Carlo cross-check of Section 6 possible. It shows that the deflator is strictly increasing in the elapsed time when a > 0, which is the precise sense in which capacity suppresses growth. And it locates the analytical obstruction: the law of the exponential functional is known in closed form only through the results of Dufresne [17] and Yor [18], whose densities are expressed through modified Bessel functions and do not combine with a call payoff to give an elementary formula. This justifies the numerical treatment that follows, and replaces the customary and unsupported assertion that no closed-form solution exists.
6Numerical method and validation
6.1Discretisation
Equation (6) is solved backwards in time on the truncated domain [0, Smax] with a uniform grid of M + 1 nodes in space and Nt steps in time. Central differences are used in space,
so that the discrete spatial operator is
and the time stepping is the θ-scheme
with θ = 1/2 (Crank–Nicolson). Because the payoff has a kink at the strike, pure Crank–Nicolson produces spurious oscillations in the Greeks; the scheme is therefore started with four fully implicit half-steps in the manner of Rannacher [20], after which second-order accuracy is restored [21]. Each step requires the solution of a tridiagonal system, carried out by the Thomas algorithm, so the cost is linear in M.
6.2Stability and monotonicity
The Crank–Nicolson scheme is unconditionally von Neumann stable, but two practical conditions are respected. If an explicit variant is used the time step must satisfy
and central differencing of the convective term remains monotone only when the cell Péclet number satisfies
Condition (21) is the reason the logistic drift deserves attention in the discretisation: the factor (1 − S/N) changes sign at S = N, and for small carrying capacity the drift is largest exactly where the grid is coarsest in relative terms. In the computations reported below, Smax = 4 max(s, K) and M ≥ 800, under which (21) holds at every interior node; upwinding was not required.
6.3Validation against the closed-form limit
Setting N → ∞ reduces the model to Black–Scholes–Merton, for which an exact formula is available. Table 1 reports the error under simultaneous grid refinement for s = K = 100, r = 0.05, q = 0.02, σ = 0.20 and T = 1.
| Grid (M × Nt) | Call | Call error | Put error | Order |
|---|---|---|---|---|
| 100 × 100 | 9.1882 | 3.88e-2 | 3.87e-2 | — |
| 200 × 200 | 9.2174 | 9.63e-3 | 9.63e-3 | 2.01 |
| 400 × 400 | 9.2246 | 2.41e-3 | 2.40e-3 | 2.00 |
| 800 × 800 | 9.2264 | 6.01e-4 | 6.01e-4 | 2.00 |
| 1600 × 1600 | 9.2269 | 1.50e-4 | 1.50e-4 | 2.00 |
Reference values from the Black–Scholes–Merton formula with a dividend yield: call 9.2270, put 6.3301. The observed order of convergence approaches two, as expected for Crank–Nicolson with Rannacher start-up.
The errors fall by a factor of four at each refinement and the estimated order is 2.00, confirming that the implementation attains the theoretical rate and that the vanishing-gamma boundary treatment does not degrade accuracy.
6.4Cross-validation by Monte Carlo
For finite carrying capacity no closed-form benchmark exists, so the scheme is checked against Monte Carlo simulation of the representation (15), using 400,000 paths, 1,000 time steps and the trapezoidal rule for the functional. Table 2 reports the comparison.
| N | Call, PDE | Call, MC (s.e.) | Put, PDE | Put, MC (s.e.) |
|---|---|---|---|---|
| 150 | 7.9990 | 7.9658 (0.0201) | 7.0910 | 7.1038 (0.0152) |
| 200 | 8.2938 | 8.2599 (0.0205) | 6.8963 | 6.9088 (0.0150) |
| 400 | 8.7511 | 8.7161 (0.0212) | 6.6097 | 6.6218 (0.0148) |
Parameters as in Table 1. Standard errors in parentheses. Every PDE value lies within approximately two standard errors of the simulated value; refining the simulation to 16,000 time steps removes the residual discretisation bias.
7Numerical results and sensitivity analysis
Unless stated otherwise the base case is s = 100, K = 100, r = 0.05, q = 0.02, σ = 0.20 and T = 1, and all values are computed on a 1600 × 1600 grid.
7.1Effect of the carrying capacity
| Carrying capacity N | Call | Put |
|---|---|---|
| 110 | 7.5844 | 7.3794 |
| 125 | 7.7689 | 7.2489 |
| 150 | 7.9990 | 7.0910 |
| 200 | 8.2938 | 6.8963 |
| 300 | 8.5967 | 6.7045 |
| 500 | 8.8448 | 6.5532 |
| 1000 | 9.0343 | 6.4410 |
| ∞ (BS) | 9.2270 | 6.3301 |
Base-case parameters. The final row is the Black–Scholes–Merton limit.
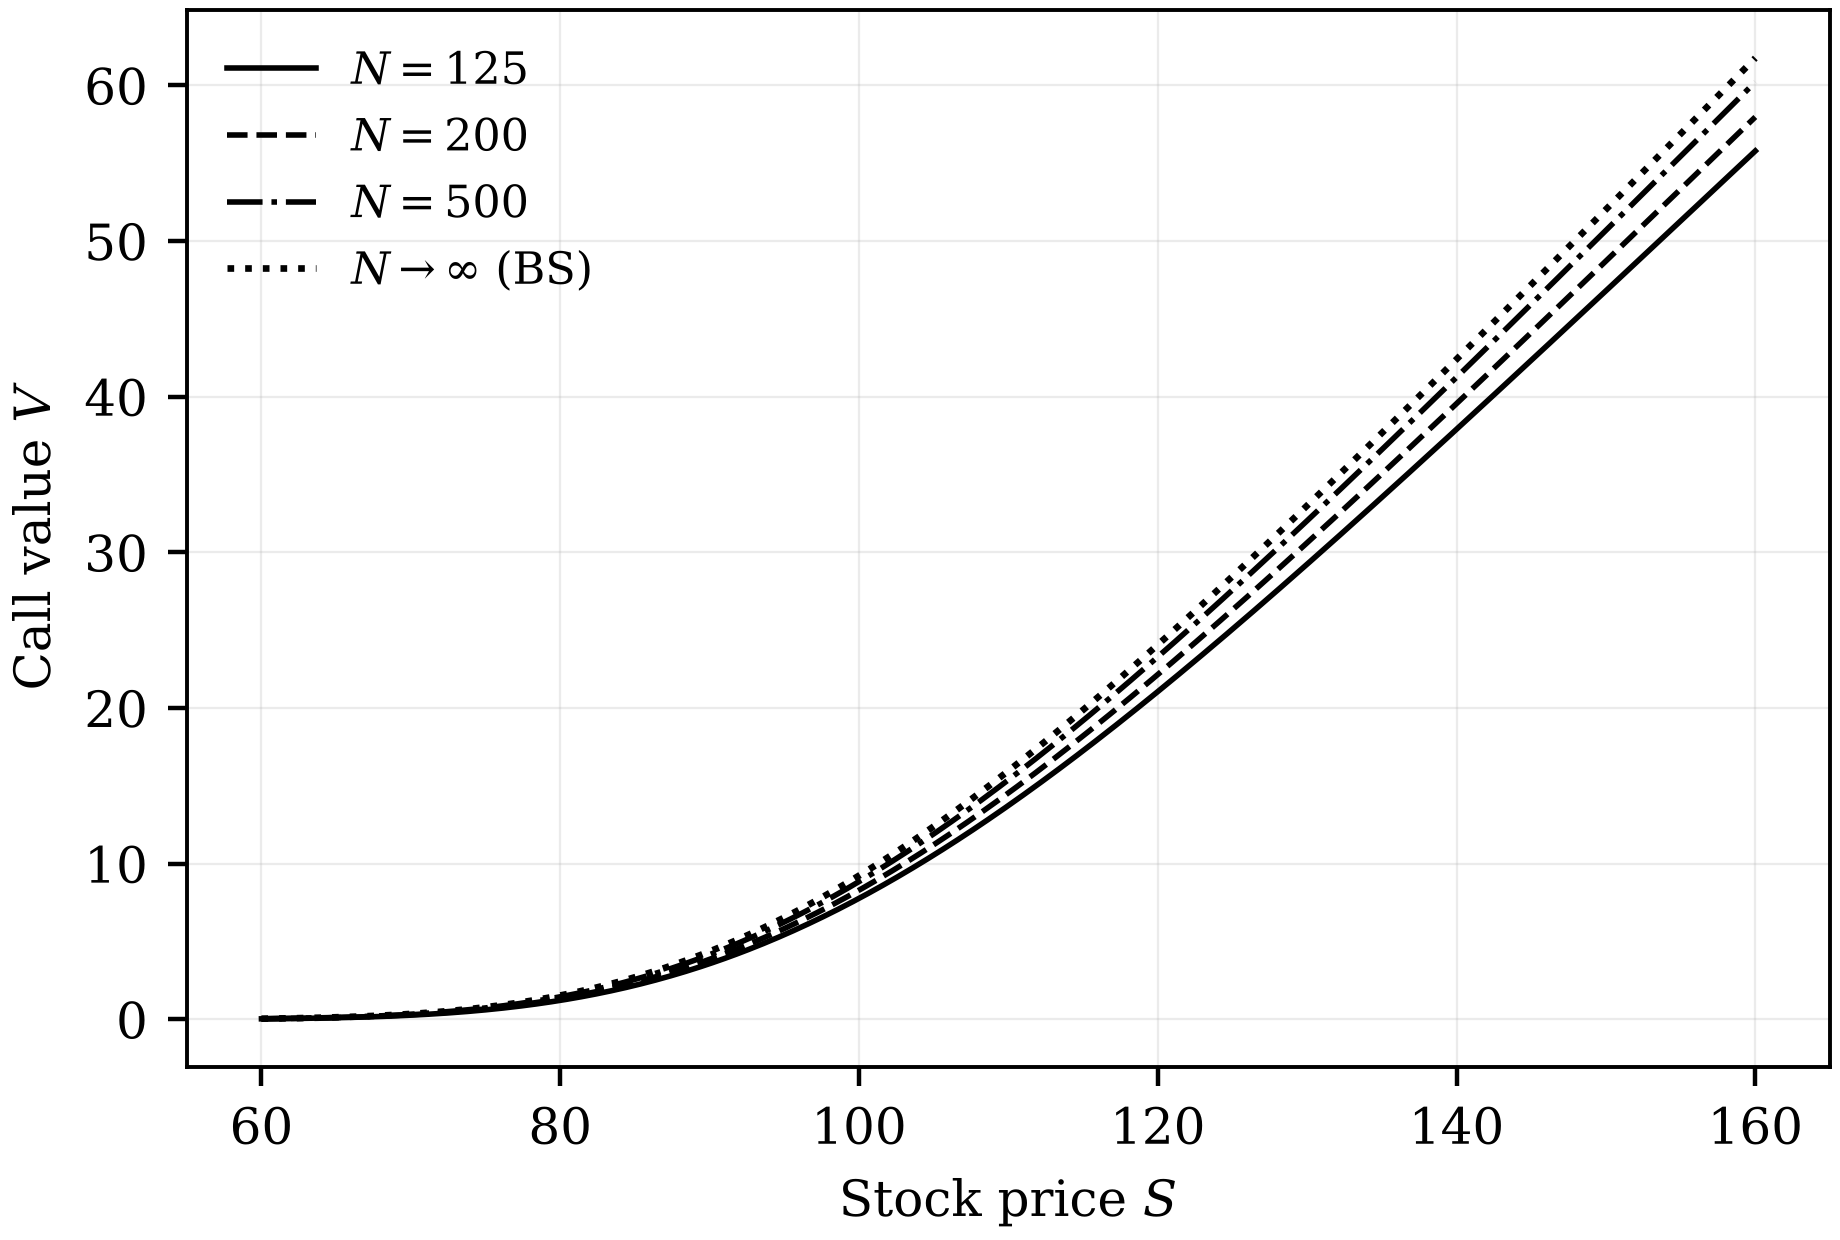
Table 3 shows that call values increase monotonically in N and put values decrease, converging to the Black–Scholes–Merton values from below and above respectively. The effect is economically material: at N = 125, that is a ceiling 25 per cent above the spot price, the call is 15.8 per cent cheaper and the put 14.5 per cent dearer than under geometric Brownian motion. The mechanism is visible in Figure 1: capacity truncates the upper tail that a call is paid from, and the same truncation supports put values by holding the distribution down.
7.2Effect of the dividend yield
| q | Call, N = 200 | Call, BS | Put, N = 200 | Put, BS |
|---|---|---|---|---|
| 0.00 | 8.7937 | 10.4506 | 6.4650 | 5.5735 |
| 0.02 | 8.2938 | 9.2270 | 6.8963 | 6.3301 |
| 0.04 | 7.8115 | 8.1026 | 7.3456 | 7.1466 |
| 0.06 | 7.3468 | 7.0755 | 7.8128 | 8.0220 |
| 0.08 | 6.8998 | 6.1430 | 8.2979 | 8.9543 |
Base-case parameters except for q.
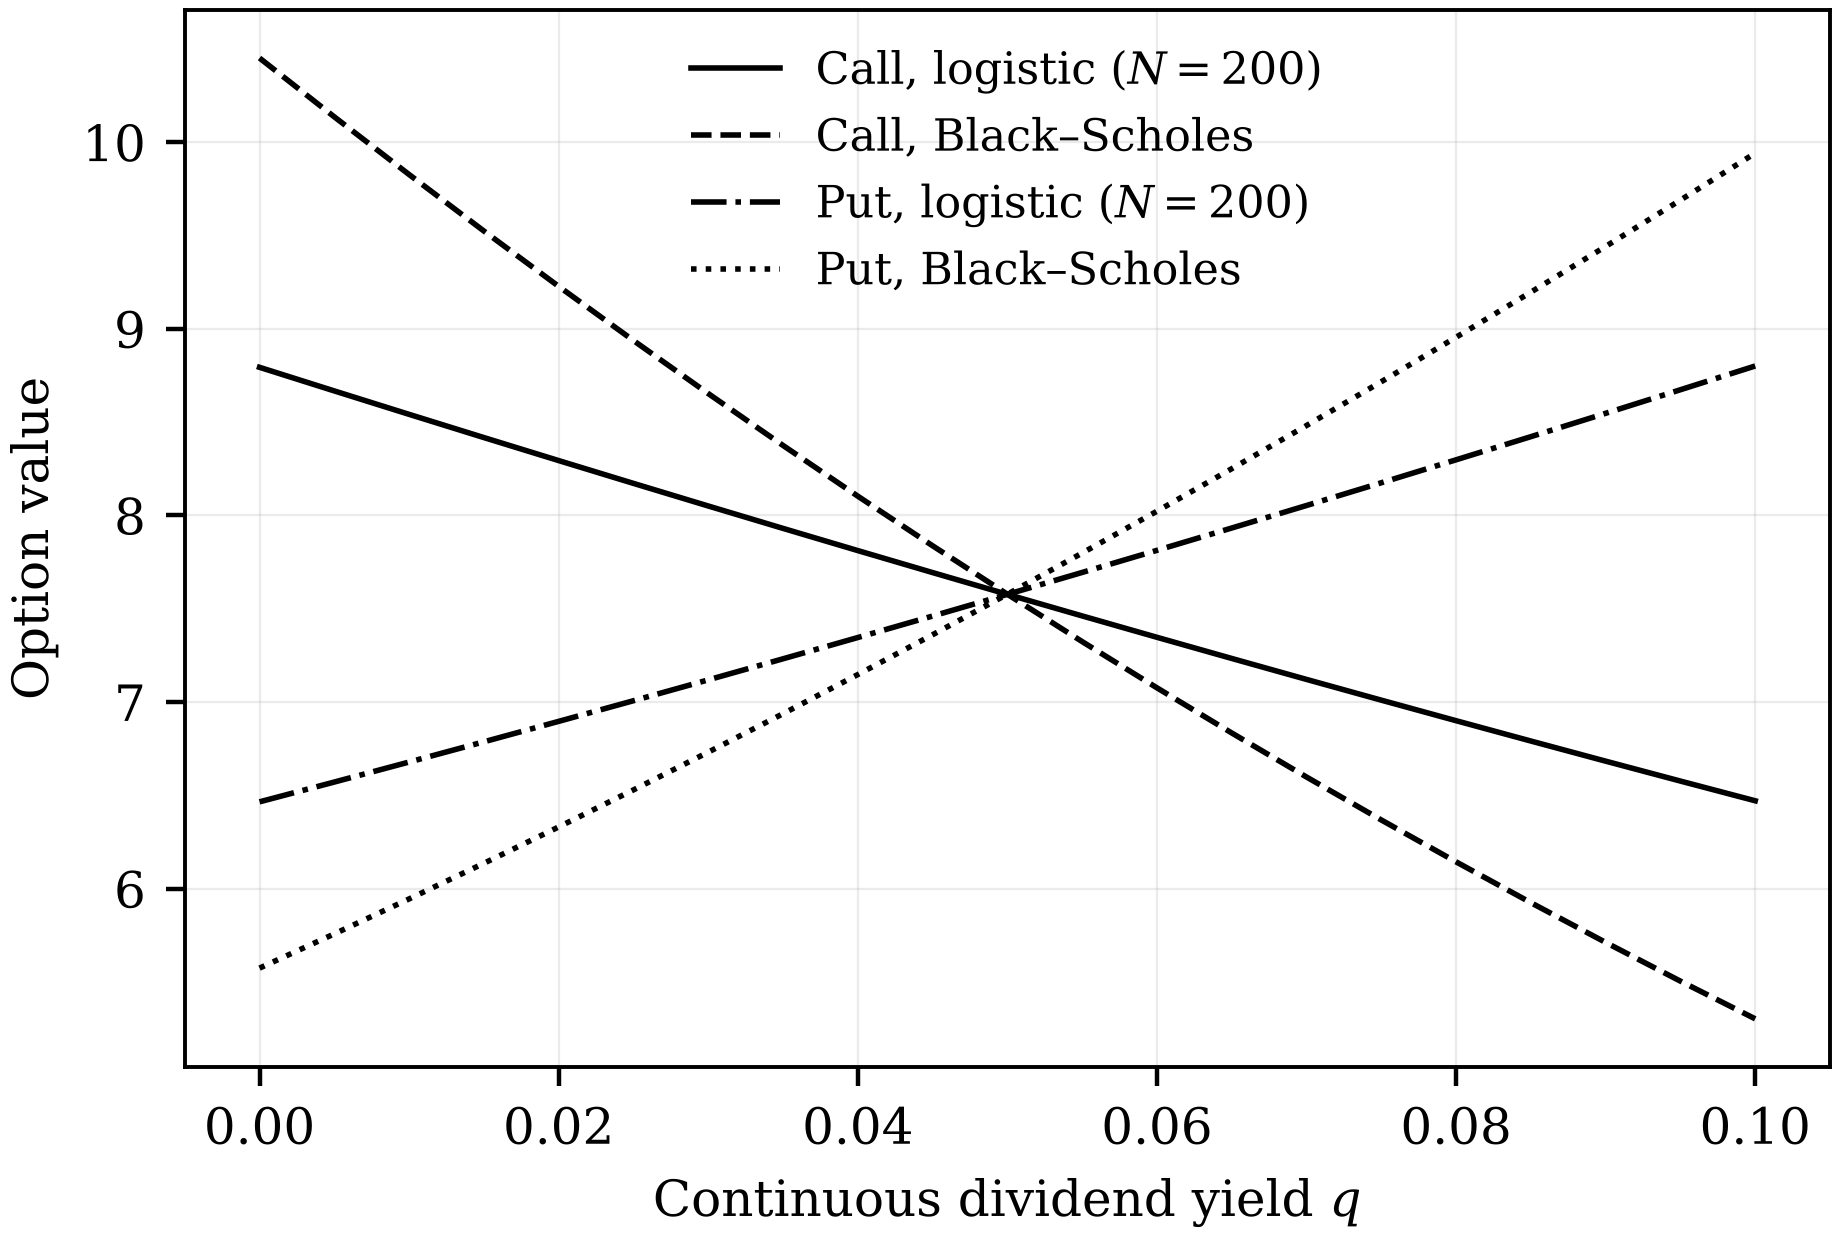
Calls fall and puts rise in the dividend yield (Table 4), as in the classical model, but the logistic response is markedly flatter. Raising q from zero to 0.08 reduces the call by 21.5 per cent under logistic dynamics against 41.2 per cent under Black–Scholes. The reason is structural: q enters the model twice, once by reducing the risk-neutral growth rate and once, with the opposite sign, by weakening the capacity brake, since a smaller a shrinks the term aS(1 − S/N). Capacity-constrained assets are thus less dividend-sensitive, which is the clearest empirically testable prediction of the model. Figure 2 shows the crossing of the two families of curves.
7.3Effect of volatility
| σ | Call, N = 200 | Call, BS | Put, N = 200 | Put, BS |
|---|---|---|---|---|
| 0.10 | 4.5444 | 5.4713 | 3.1249 | 2.5744 |
| 0.15 | 6.4186 | 7.3369 | 5.0082 | 4.4399 |
| 0.20 | 8.2938 | 9.2270 | 6.8963 | 6.3301 |
| 0.30 | 12.0277 | 13.0203 | 10.6677 | 10.1234 |
| 0.40 | 15.7239 | 16.7994 | 14.4185 | 13.9024 |
Base-case parameters except for σ.
Both calls and puts increase in volatility (Table 5), and the logistic discount on calls is roughly proportional across the range, narrowing slightly as volatility rises because diffusion then dominates drift. Vega remains positive throughout, so the model does not disturb the qualitative behaviour on which volatility trading rests.
8The forward-price diagnostic
Because the risk-neutral drift in (4) is not that of a traded asset, the discounted price is not a Q-martingale, and put–call parity cannot hold exactly. The size of the violation is a measure of how far the model departs from the traded-asset case, and it is reported here rather than suppressed. Define the model-implied forward and the traded forward by
A first-order expansion of the representation (15) in 1/N gives
and evaluating the expectation of the product of the geometric Brownian motion and its integral yields the relative bias
Table 6 compares this expression with the bias measured from the computed option prices.
| N | Implied forward | Bias, measured (%) | Bias, formula (%) |
|---|---|---|---|
| 125 | 100.547 | -2.425 | -2.486 |
| 150 | 100.955 | -2.029 | -2.072 |
| 200 | 101.469 | -1.530 | -1.554 |
| 300 | 101.989 | -1.025 | -1.036 |
| 500 | 102.409 | -0.618 | -0.621 |
| 1000 | 102.726 | -0.310 | -0.311 |
Base-case parameters; the traded forward is 103.045. Measured bias is computed from the Crank–Nicolson call and put values through (22); the formula column is (24).
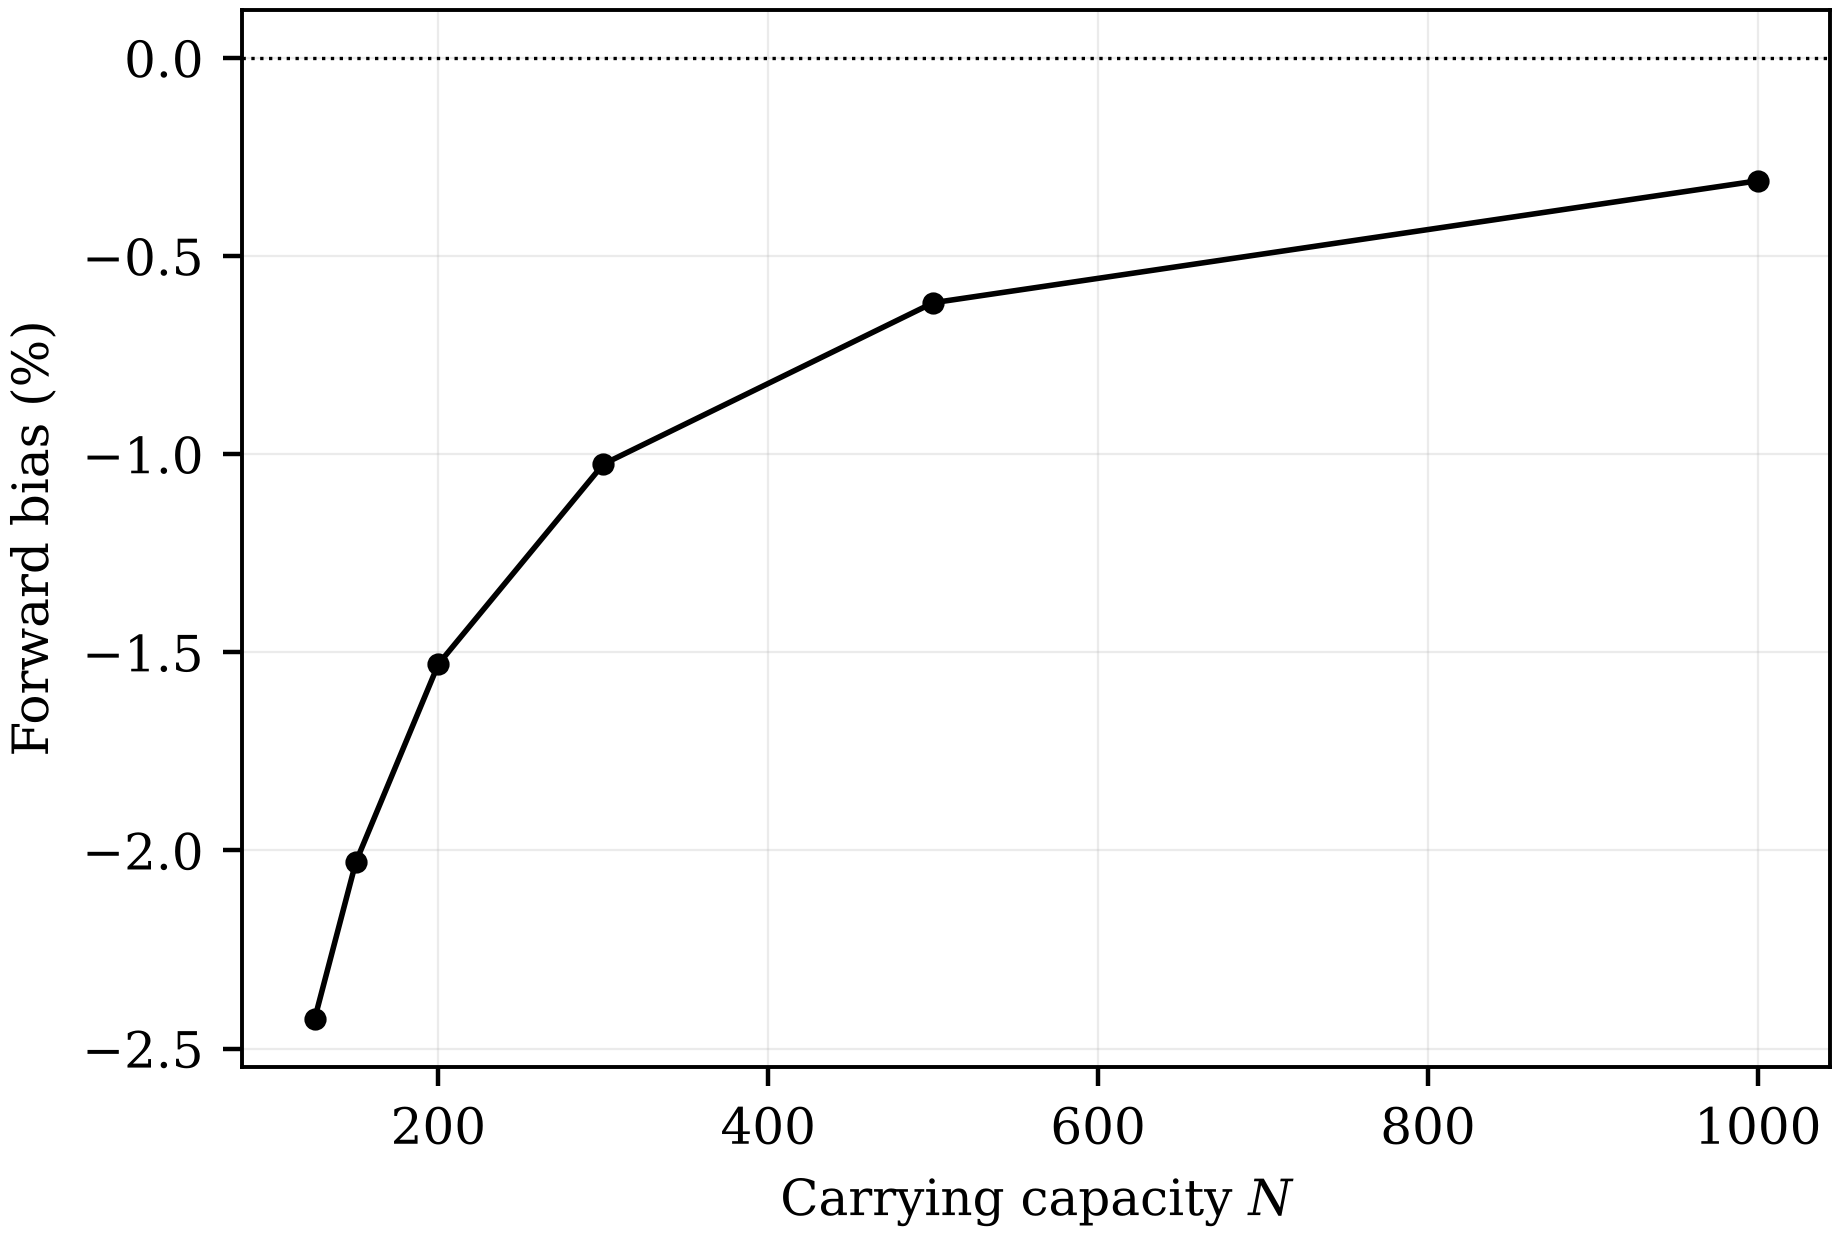
The analytic expression tracks the measured bias closely (Figure 4) and the agreement improves as N grows, as a first-order expansion should. The practical readings are these. The bias is negative, so the model prices the synthetic forward below the traded forward, and it scales as 1/N: at a capacity ten times spot the violation is about 0.31 per cent, at a capacity 1.25 times spot it reaches 2.4 per cent. If the underlying is genuinely traded and liquid, a violation of that size is an arbitrage and the model must not be used. If the underlying is not traded, or if trading is constrained by the capacity mechanism the model is designed to represent, the violation is instead the model’s estimate of how far the capacity constraint moves the effective forward, and it is the quantity a practitioner should compare against observed forward or futures quotes when deciding whether to adopt the model.
9Calibration
9.1Volatility
From n log-returns observed at spacing Δt the annualised volatility estimator is
The factor in Δt is required for annualisation and is frequently omitted. Under logistic dynamics the log-returns are not identically distributed, since the drift depends on the level of the process, so this estimator is consistent for σ but is not efficient; a maximum-likelihood or realised-variance estimator is preferable when intraday data are available.
9.2Carrying capacity and growth rate
The pair (μ, N) is estimated by non-linear least squares on the drift of the discretised log-return,
Two cautions apply. The first is that μ does not enter the pricing equation at all: under the selected measure it has been replaced by r − q, so only N is needed for pricing, and μ matters for risk management and for the specification of the market price of risk (3). The second is identification. When the observed sample stays far below the capacity the two parameters are nearly collinear, the objective is flat along a ridge, and N is estimated imprecisely. In that situation N should be treated as a structural quantity taken from market-size information, such as the total addressable market, the licensed subscriber ceiling or the free float, rather than estimated from price history.
9.3Dividend yield
The dividend yield is estimated directly from the payout record,
and should be measured over a period long enough to smooth the payout cycle.
10Discussion
The results support three conclusions. First, a logistic option pricing model is coherent only as an incomplete-market model. This is not a technicality but the central structural fact, and it fixes both the derivation route, which is Feynman–Kac rather than delta hedging, and the interpretation of the output, which is a price under a selected measure rather than a replication cost. Second, capacity has a first-order effect on option values. A ceiling 25 per cent above spot moves a one-year at-the-money call by about 16 per cent, which is far larger than typical bid-ask spreads and is therefore economically meaningful. Third, the model makes a distinctive and testable prediction, namely that capacity-constrained assets are substantially less dividend-sensitive than the classical model implies.
The limitations are equally clear. The pricing measure is selected rather than implied, so prices inherit the market price of risk assumed in (3); a different choice would change them, and the model is not preference-free. The carrying capacity is assumed constant, whereas market size evolves, and a stochastic or time-dependent N would be more realistic at the cost of an additional state variable. The parity violation quantified in Section 8 is a genuine constraint on the model’s domain of application, not an artefact of the numerics. Finally, no empirical estimation is attempted here; the model is developed and validated numerically, and confronting it with market option data is the natural next step.
11Conclusion
This paper has developed a European option pricing model under logistic stock-price dynamics with a continuous dividend yield. The delta-hedging derivation used elsewhere in the logistic literature was shown to eliminate the logistic drift it is meant to preserve; the model was therefore constructed as an incomplete-market model with an explicit state-dependent market price of risk, and the pricing equation was obtained from the Feynman–Kac representation. The equation is linear, carries the dividend yield through the cost-of-carry, and reduces to the Black–Scholes–Merton equation as the carrying capacity grows without bound.
A closed-form representation of the price process was derived through the reciprocal transformation, expressing the price as a geometric Brownian motion deflated by an exponential functional whose law is the true source of analytical difficulty. A Crank–Nicolson scheme with Rannacher start-up was specified, shown to converge at second order against the closed-form limit, and cross-validated against Monte Carlo simulation. The sensitivity analysis quantified the effects of capacity, dividend yield and volatility, and a forward-price diagnostic with a first-order analytic expression measured the model’s departure from put–call parity.
Further work should address a stochastic or time-varying carrying capacity, American and path-dependent payoffs under the same generator, hedging strategies under the selected measure with an explicit treatment of the residual risk, and empirical calibration to option quotes on assets with identifiable capacity constraints.
References
- [1]Black F, Scholes M. The pricing of options and corporate liabilities. Journal of Political Economy. 1973;81(3):637–654. https://doi.org/10.1086/260062
- [2]Merton RC. Theory of rational option pricing. Bell Journal of Economics and Management Science. 1973;4(1):141–183. https://doi.org/10.2307/3003143
- [3]Cox JC, Ross SA. The valuation of options for alternative stochastic processes. Journal of Financial Economics. 1976;3(1–2):145–166. https://doi.org/10.1016/0304-405X(76)90023-4
- [4]Derman E, Kani I. Riding on a smile. Risk. 1994;7(2):32–39.
- [5]Dupire B. Pricing with a smile. Risk. 1994;7(1):18–20.
- [6]Kou SG. A jump-diffusion model for option pricing. Management Science. 2002;48(8):1086–1101. https://doi.org/10.1287/mnsc.48.8.1086.166
- [7]Merton RC. Option pricing when underlying stock returns are discontinuous. Journal of Financial Economics. 1976;3(1–2):125–144. https://doi.org/10.1016/0304-405X(76)90022-2
- [8]Mulambula A, Oduor DB, Kwach BO. Volatility estimation using European logistic Brownian motion with jump diffusion process. School of Mathematics and Actuarial Sciences, Jaramogi Oginga Odinga University of Science and Technology; 2020.
- [9]Nyakinda JO. Derivation of a non-linear logistic Black–Scholes–Merton partial differential equation [PhD thesis]. Jaramogi Oginga Odinga University of Science and Technology; 2011.
- [10]Oduor DB, Omolo ON, Okelo NB, Onyango SN. Estimation of market volatility: A case of logistic Brownian motion. International Journal of Marketing and Technology. 2012;2(1):32–48.
- [11]Onyango SN. Extracting stochastic processes from market price data: A pattern recognition approach [PhD thesis]. Huddersfield, UK: University of Huddersfield; 2003.
- [12]Heston SL. A closed-form solution for options with stochastic volatility with applications to bond and currency options. Review of Financial Studies. 1993;6(2):327–343. https://doi.org/10.1093/rfs/6.2.327
- [13]Verhulst PF. Notice sur la loi que la population suit dans son accroissement. Correspondance Mathématique et Physique. 1838;10:113–121.
- [14]Karatzas I, Shreve SE. Methods of mathematical finance. New York: Springer; 1998.
- [15]Duffie D. Dynamic asset pricing theory. 3rd ed. Princeton, NJ: Princeton University Press; 2001.
- [16]Björk T. Arbitrage theory in continuous time. 3rd ed. Oxford: Oxford University Press; 2009.
- [17]Dufresne D. The distribution of a perpetuity, with applications to risk theory and pension funding. Scandinavian Actuarial Journal. 1990;1990(1–2):39–79.
- [18]Yor M. On some exponential functionals of Brownian motion. Advances in Applied Probability. 1992;24(3):509–531.
- [19]Crank J, Nicolson P. A practical method for numerical evaluation of solutions of partial differential equations of the heat-conduction type. Proceedings of the Cambridge Philosophical Society. 1947;43(1):50–67. https://doi.org/10.1017/S0305004100023197
- [20]Rannacher R. Finite element solution of diffusion problems with irregular data. Numerische Mathematik. 1984;43(2):309–327. https://doi.org/10.1007/BF01390130
- [21]Giles MB, Carter R. Convergence analysis of Crank–Nicolson and Rannacher time-marching. Journal of Computational Finance. 2006;9(4):89–112.